Showing posts with label Stocks. Show all posts

Saturday, August 15, 2015

On share buybacks

A Share buybacks is a common action taken by corporations mostly to improve their ratios. In addition, a buyback is expected to push up the share price. This in turn, help executives meet their targets.

In last week`s The Economist, it was mentioned that the supply of equities may soon stop shrinking. A slowdown is expected in the second half of the year as profits have been out of steam and firms have less cash to deploy. 

The Harvard Business Review has a good article regarding this issue. 

Thursday, August 6, 2015

Update on Citadel

The Wall Street Journal  has an excellent write up on Citadel and the hedge fund`s boss, Ken Griffin.The fund survived the 2008 crisis after disastrous losses and is now expanding aggressively. Ken Griffin said it took him some 3 years to make back the losses.

Ben Bernanke, the former Federal Reserve Chair is a part-time consultant in the hedge fund.

Other interesting bits about his hedge fund include:
- The leverage ratio is 7:1. For every $1 invested by customers, Citadel borrows $7.
- An ex-Amazon employee with a machine learning background was hired as the mathematical techniques have applicability in financial markets.

The interview with Ken Griffin can be found here.

Friday, July 31, 2015

Late day jolts in China stocks

The Wall Street Journal has a write up on what has been the force in driving late day jolts. The two factors identified were:

1) Afternoon margin calls from lenders.
2) Presence from authorities.

Monday, July 6, 2015

Bursa Q2 recap


The second quarter has been a disaster for Bursa. On 29 June, the index dipped below 1700 points. The companies that represent the index have been falling in term of prices. In addition, CIMB is offering 11% of its work force the VSS (voluntary separation scheme) while Axiata plans to trim its work force by 20%.


Historical data was obtained from Yahoo Finance.

Monday, May 25, 2015

KLSE below the 1800 phychological barrier

The KLSE index closed some 20.12 points lower today, representing a 1.13% drop.


This is the closing level of the KLSE index from 1/4/2015 to 25/5/2015. Data was obtained from Yahoo Finance.


The first significant drop below 1800 was on 21/5 and it has been downwards since then. It is not usual for the index to drop 1% or more in a day. The average index gain per year over the long term is around 10%, with a drop like this, it takes just 10 days to wipe out an entire year`s gain.

The only good news is that the index is just slightly above the level of the first trading day of the year. Check out my earlier post for the first quarter recap.

In short, if one had bought the index on the first day of the year, the gain to date is a mere 0.8%.


Wednesday, April 15, 2015

Julian Suresh Caniah has been buying up Cliq

Julian Suresh Caniah, a director of Cliq Bhd has been buying up the company`s shares.

Over the last two weeks, he has purchased 1.1 million shares bringing his ownership to a total of 22.5 million shares. This represents a 3.57% direct interest in the company.


Cliq is artificially pushed down

Both the mother share and WA call warrant have been pushed down, exactly at 4.50.00 pm. Why this particular timing is significant is that after 4.50.00 pm, traders can only buy or sell at the last done price. Obviously none of the current warrant holders would sell their in the money warrants at this price.


Notice how precise the timing was to push down the mother share.


The same can be seen in the WA call warrant.


Since it was done precisely at 4.50.00 pm, buyers could not offer more than RM 0.125 while sellers will not release their warrants at this price.

Monday, April 13, 2015

Genting C20 is trading at a discount of 4.7%

Genting C20 is in the money but is has been stubborn to match. It has not moved all day up to now. 


The mother share has fallen by 10 cents but the C20 call warrant has not moved yet. Usually, a movement in the price of the mother share would trigger an even more drastic change in its warrant/s percentage wise.


Here is a snapshot of the term sheet. 


As of this post, the C20 call warrant is trading at a discount of 4.7%. 

Sunday, April 12, 2015

Hovid WB is still trading at a discount

This is a follow up to my post on Hovid on March 30th. The WB call warrant has since appreciated by 17.6% while the mother share is up by 12.5%.


The strike price for this warrant is RM 0.18 with an exercise ratio of 1:1, making being priced at a discount of 3%.


Thursday, April 9, 2015

More gains for Cliq WA

Following my post yesterday on this particular call warrant, it went up again today.


Wednesday, April 8, 2015

When the mother share appreciates...

Cliq appreciated by the slighted bit today


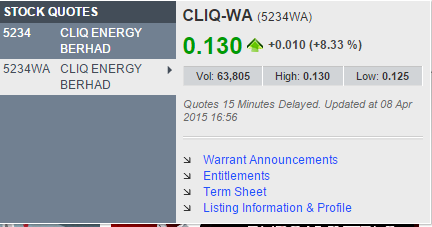
And since a warrant is related to its mother share, guess what? The WA call warrant jumped by 8.33% today.


This appreciated was much expected based on my analysis on Monday for my group members before trading started. 


Wednesday, April 1, 2015

Bursa Index Q1 recap


It has been a positive first quarter for Bursa. Historical data was obtained from Yahoo Finance.


Tuesday, March 31, 2015

An update on Hovid WB and its mother share

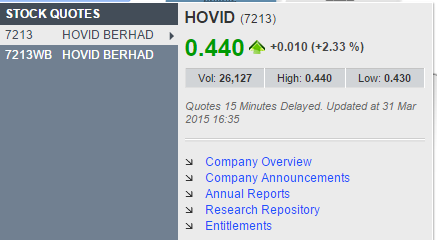
In my earlier post, Hovid WB was one of the warrants I identified with the potential to appreciate. At the pre-closing, the last done price for the mother share and WB warrant is RM 0.44(+2.3%) and RM 0.25(+4.2%) respectively.


The call warrant is still in the money as it is trading at a 1.1% discount. To put this in layman terms, due to inefficiencies in the market, theoretically there`s a risk free profit of 1.1% to be made. 

Monday, March 30, 2015

Harta CM up by 14.6% today


I completed my analysis pretty late today, just 15 minutes before the market opened.


Harta CM was the best performer today with a 14.634% appreciation in a day.

Here is the breakdown of the specifications of this call warrant:
- Exercise ratio: 6
- Strike price: RM 5.70

Thursday, March 26, 2015

Sunway CI remained in the money till the end

On Sunday I posted on instagram my analysis on a couple of in the money call warrants on Bursa.


Sunway CI is number 6 in the list and I highlighted it due to it`s relevance. At the time I posted the table, it was in the money, with a 6.25% discount. I cannot say that it is 100% risk free to profit, but it is nearly risk free.

The last trading day for this warrant was yesterday and the final price remained at RM 0.155. The mothershare closed at RM 3.63 today.

To put this into perspective, for every 10 000 units of the CI warrant, the cost is RM 1 550 with a profit of RM 300. This is nearly a 20% gain, not bad for a trade that lasted for only a couple of days.

Sunday, January 18, 2015

KLCI update: Week 3 at 1743.57

The index closed at 1743.57 points on Friday, a tiny gain for the week. The central bank, Bank Negara did not inspire much confidence in investors when it made the statement that it`ll not intervene in foreign exchange rates. The Ringgit has plummeted badly in recent months, making it the second worst performing currency in Asia after Japan. 

Overall, the outlook is still gloomy for KLCI with nothing fundamentally concrete to push the index up and gain its much needed foreign investors. 

Wednesday, January 7, 2015

KLCI midweek update


As of the pre-opening today, the KLCI index is just slightly over 1700 points. It shed 20.04 points yesterday, representing a 1.15% drop which is quite significant.

The aftermath of cheap oil prices have taken its toll on Malaysia`s stock market. Add the fact that the Prime Minister is down with E.coli, buying interest isn`t present.

Clarence Lim, a trading associate mentioned that foreign buyers are the ones who can potentially lift up the market.

Friday, October 17, 2014

Tune Ins

Tune Ins was my favourite counter last year as it had solid fundamentals and its price range was easy to predict. It peaked to nearly RM 2.50 this year before dropping below RM 2 this week. Here are my findings from the 2013 annual report.

Income related: 

- Revenue growth of 30.85% (geometric growth).
- Net claims increased by 116%.
- Net claims rate per revenue of 24.2% in 2013 as opposed to 19.18% in 2012.
- Fees and commission expenses nearly doubled.
- Finance costs dropped to just 20% of the cost in 2012.
- Management expenses nearly doubled.
- EPS of 9.29 cents in 2013 versus 16.25 cents in 2012.

Cash flow related:

- Net cash from operating activities dropped by RM 30 million in 2013.
- Investing activities only used RM 2.7 million in 2013 compared to RM 79.2 million in 2012.
- Financing activities show a positive inflow of cash due to the issue of new shares.

Notes to the financial statements:

- In Note 17, the company was given a loan of RM 160 million. The weighted average effective interest rate at 6.25% is way higher than a standard bank loan.


Valuations 

1. Book value plus model would put it at RM 0.52 per share.
2. EVA gives a meager RM 0.07 per share.

Intrinsically this counter is not at a discount. The fundamentals may be solid, but its charm has slightly eroded compared to its performance last year.

Tuesday, October 14, 2014

Potential in Censof?

A number of friends have added Censof Holdings Bhd (Censof) to their portfolio. Let`s take a look at this counter`s intrinsic value. Censof is not undertaking any mergers or acquisitions exercise, hence the valuation techniques used are from my part 1 article.

The values used for this post are derived from the 2014 annual report.

1) Book value plus model


(RM)`000
Total value of net assets
411 722
Less: Intangibles
63 554
Non-current liabilities
(76 862)
Net value of equity
398 414


Total number of shares (Note 16 in the financial statements) = 399 576 (`000)

Value per share = Net value of equity / total number of shares
                          = 398 414 / 399 576
                          = 0.997

The book value plus model gives an intrinsic value of close to RM 1 per share. 


2) Economic Value Added (EVA)

Weighted average cost of capital (WACC) calculation:

(i) Cost of equity = Dividends per share/ Share price
(Note: I`ll assume the share price used for this calculation is the market value today, which is RM 0. 585)
                            = 0.01 / 0.585
                            = 0.0171
                            = 1.71%

(ii) Cost of debt
Ignoring any adjustments, I`ll use the interest paid over total borrowings.

                           = 3 835 / 152 549
                           = 0.0251
                           = 2.51% 

(iii) WACC = [ 0.0171(39 960) + 0.0251(152 549)] / 39 960 + 152 549
                    = 0.0234

                    = 2.43%


EVA = NOPAT - (WACC x Book value of capital employed)
         = 4 129 - 0.0243(39 960)

         = 3 157.97

Value per share = 3 157.97 / 399 576

                          = 0.0079

EVA would give this counter a value of RM 0.0079 per share.  


3) Market Value Added (MVA) 


The MVA is simply the present value of EVA and in line with, it gives too low a value for a meaningful comparison.


Conclusion 
If compared to the book value plus model, this counter is trading at a discount. However, the economic profits are meager which should raise the alarm for value investors. In addition, the level of debt of this company is rather high, exceeding the value of equity. 

Regular, accounting profits would give an earnings of RM 0.30 per share. This translates to every RM 1 invested in Censof makes RM 0.51. 

Saturday, October 11, 2014

US indices are taking a beating

Go over to bloomberg for the article.

S&P 500 dropped 1.1% to 1906.13 points. This is more bad news for Bursa.

Mr Clarence, a trading associate predicted that Bursa Malaysia will fall below 1800 on Monday and a recession is scheduled for 2016.